Aktis Oncology priced the first biotech IPO of 2026 on January 8 — 17,650,000 shares at $18.00, the top of its $16–18 range, upsized 50% in the three days before pricing — with Eli Lilly buying $100 million of the deal itself. As of the September 4 close, AKTS trades at $27.05, +50.3% versus offer.
TL;DR — Aktis (Nasdaq: AKTS) raised $318M gross at pricing ($365M with the greenshoe, exercised in full; net $334.4M) on a Phase 1 radiopharmaceutical pipeline — the earliest-stage profile among the class’s large-deal winners. The structure set the year’s template: upsized at the top of range, a strategic anchor inside the book (Lilly’s 5,555,555 shares were 31.5% of the base deal), full greenshoe, and a +24.4% debut that held. Performance figures are marked to the September 4 close; prices move daily. Caveat: the lead asset’s first efficacy data are not due until Q1 2027, so the +50% mark is strategic validation and modality scarcity being priced ahead of data.
This is a per-company companion to our 2026 IPO class deep-dive. The class story started here: Aktis priced two days into the new year, and the deals that followed — Kailera, Parabilis, Veradermics — repeated its structure with bigger checks.
The asset: actinium-225 miniprotein radioconjugates, imaging-guided
The lead program is [225Ac]Ac-AKY-1189, a miniprotein radioconjugate targeting Nectin-4 — the same target as Pfizer’s Padcev — carrying an actinium-225 alpha payload. It is in Phase 1b in previously treated urothelial cancer and other Nectin-4-positive solid tumors (breast, NSCLC, colorectal, cervical): the NECTINIUM-2 trial, NCT07020117, ~150 patients, recruiting, primary completion estimated December 2027. The 424B4 calls it the first miniprotein radioconjugate ever advanced into human studies. Per BioPharma Dive’s IPO-day report, Phase 1 results are expected in Q1 2027.
The second program, [225Ac]Ac-AKY-2519 (B7-H3; prostate, lung, breast), was in human clinical imaging at IPO and has since advanced to a Phase 1b in metastatic castration-resistant prostate cancer — BActinium-1, NCT07581184, ~138 patients — with first-in-human imaging and dosimetry data presented at ASCO in May 2026. The platform logic: copper-64 imaging verifies target engagement before therapeutic dosing, an isotope-agnostic design intended to derisk each candidate before alpha-emitter exposure. The remaining pipeline is undisclosed discovery-stage radioconjugates, all unpartnered.
The Lilly relationship predates the IPO: a May 2024 collaboration ($60M upfront cash plus an equity investment, up to $1.2B of milestones and tiered royalties) under which Aktis runs discovery through initial human imaging and Lilly takes worldwide development from Phase 1 onward — while Aktis retains all proprietary pipeline rights. Aktis was founded and incubated by MPM BioImpact and had raised ~$346M privately (MPM, Vida Ventures, EcoR1, Blue Owl, RA Capital) before the IPO.
The deal: 50% upsize in three days, a third of the book to one buyer
| Step | Shares | Price | Gross |
|---|---|---|---|
| Marketed (S-1/A, Jan 5) | 11,775,000 | $16–18 | $188–212M |
| Upsized S-1/A (Jan 7) | 17,650,000 | $16–18 | $282–318M |
| Priced (Jan 8) — top of range | 17,650,000 | $18.00 | $317.7M |
| Greenshoe exercised in full (15%) | 20,297,500 | $18.00 | $365.4M |
Table 1: Aktis pricing steps per the Jan 5 S-1/A, the Jan 7 upsizing S-1/A, the pricing release, and the Q2 2026 10-Q (full greenshoe; net $334.4M).
The anchor was inside the deal, not alongside it. Lilly’s Schedule 13D shows 5,555,555 shares bought in the IPO at $18.00 — $100.0M, 31.5% of the base deal — on top of preferred stock that converted to another 788,559 shares, for 11.9% of the post-IPO company. Other insiders joined: MPM entities bought $20.0M and Vida Ventures 812,455 shares, per their own 13Ds. The underwriting stack — J.P. Morgan, BofA, Leerink, TD Cowen — placed the rest.
At $318M the deal was 1.08x the class median that did not yet exist when it priced — and it established the three features that would define the class: upsizing at pricing, a named strategic anchor, and full greenshoe exercise.
The tape: the pop held, then June re-rated the platform
AKTS opened its first session at $27.00 — +50% — and faded to close at $22.40 (+24.4%). It sagged to its lowest close of $15.19 on March 27 (−15.6% versus offer), the class’s early-year wobble. The re-rate came in June: from ~$19 in late May to a $32.23 closing high on June 30, around ASCO-window posters and the AKY-2519 trial-strategy and imaging disclosures. Since then: $25.78 on August 28, $27.05 on September 4.
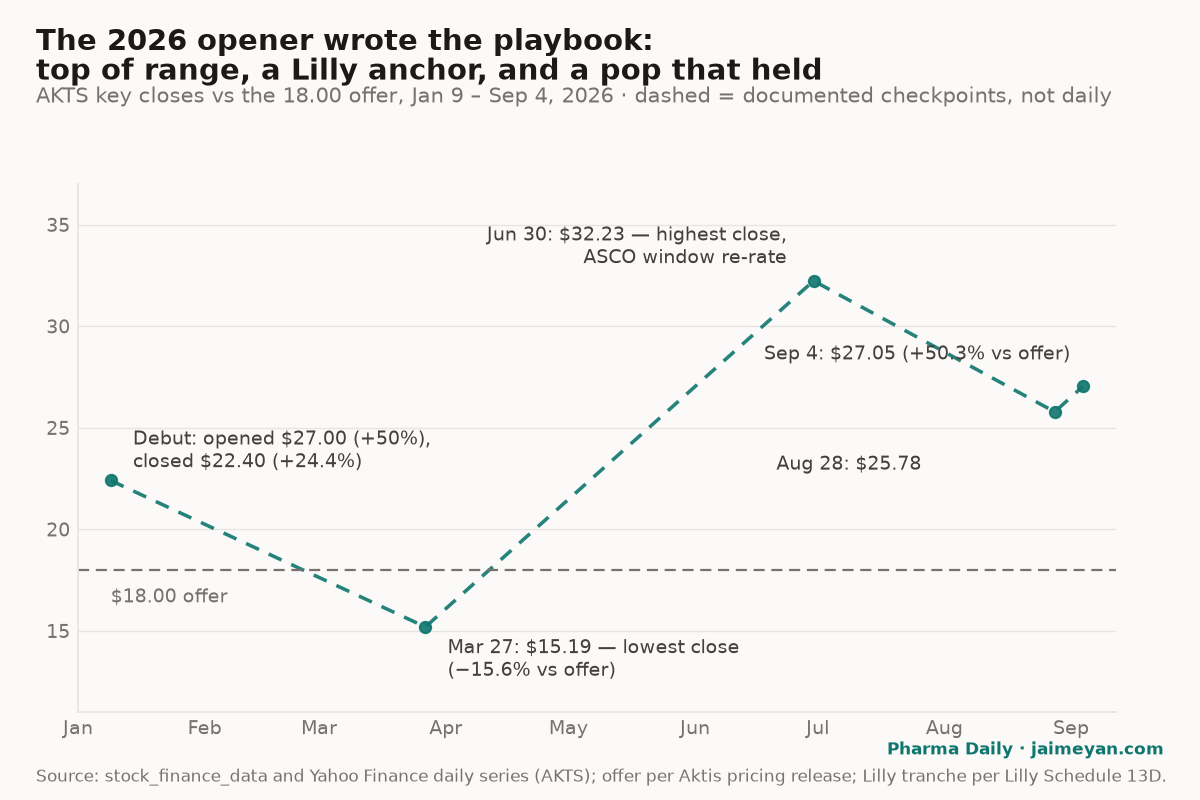
Figure 1: AKTS faded from a +50% open on debut, dipped below water in March, and re-rated in the June ASCO window — +50.3% vs offer as of September 4 with lead efficacy data still ahead (Q1 2027). Documented closes per stock_finance_data and Yahoo Finance series; dashed segments connect documented checkpoints, not a daily series.
Against the class bifurcation: Aktis is the outlier winner by stage — a Phase 1 pipeline rewarded, where Eikon’s registrational-stage platform was punished. The difference the tape appears to price is who vouched. Eikon disclosed no anchors; Aktis had its strategic partner take a third of the book at the offer price. The Q2 balance sheet supports the patience: $517.3M of cash, equivalents, and securities at June 30, a Q2 net loss of $24.1M on $25.3M of R&D, and runway guided into 2029.
What would change the story
- AKY-1189 Phase 1 data, expected Q1 2027 — the first efficacy look at the lead, and the first test of whether the imaging-guided design predicts therapeutic response.
- BActinium-1 progress (NCT07581184) — first-in-human imaging/dosimetry data presented at ASCO in May started the B7-H3 story; the dose-escalation readout cadence follows.
- Lilly’s next move — milestone activity on the collaboration, or any change to its 11.9% stake, is the anchor-signal update.
- NECTINIUM-2 enrollment — primary completion estimated December 2027; pace determines whether Q1 2027 data are interim or mature.
One Take
Aktis wrote the 2026 IPO playbook — upsize into a strategic anchor, price at the top, exercise the full shoe — and the class spent the year copying it with bigger checks. What interests me is what the anchor bought: not de-risked data (AKY-1189 was Phase 1, first efficacy due Q1 2027) but a de-risked signal, Lilly paying the offer price for a third of the deal while already holding a collaboration and preferred stock. The market has paid +50% for that signal plus a modality where strategic buyers are scarce on targets. My discomfort: the June re-rate to $32 came on imaging posters and trial-design news, not efficacy — the stock trades as if Q1 2027 is a formality, and Phase 1 single-arm data in radiopharma is exactly where “target engagement confirmed” gets misread as “response confirmed.” Conviction: moderate that AKTS holds above water into the Q1 2027 readout, because the Lilly alignment and 2029 runway remove the financing overhang that killed weaker debuts. Two falsifiers: AKY-1189 Phase 1 showing response rates that don’t clearly beat the Padcev benchmark bar the market has implicitly set, or Lilly trimming its stake — the anchor unwinding is the one signal this tape has actually traded on all year.
Key takeaways
- Aktis priced 2026’s first biotech IPO on January 8: $318M at the $18 top of range after a 50% upsize in the final week, with the 15% greenshoe exercised in full ($365M gross, $334.4M net).
- Eli Lilly bought $100M inside the IPO — 31.5% of the base deal — on top of its 2024 collaboration ($60M upfront, up to $1.2B of milestones) and preferred stock; it held 11.9% post-IPO.
- The tape: +50% open, +24.4% first close, a March dip to −15.6% vs offer, a June ASCO-window re-rate to a $32.23 closing high, and +50.3% as of September 4.
- The lead asset ([225Ac]Ac-AKY-1189, Nectin-4) is Phase 1b with first data expected Q1 2027 — the earliest-stage profile among the class’s winners; the strategic anchor substituted for late-stage data.
- Cash of $517.3M at June 30 funds operations into 2029 — no financing overhang ahead of the readout.
FAQ
Why did a Phase 1 company get the class playbook treatment?
Structure, not stage: a 50% upsize, top-of-range pricing, a $100M in-book anchor from a strategic partner, and a full greenshoe. The market priced Lilly’s conviction and the actinium-225 modality; the efficacy data that would normally justify it are due Q1 2027.
Is Lilly’s $100M a concurrent private placement?
No — unlike Regeneron’s discounted placement in the Parabilis deal, Lilly bought 5,555,555 shares inside the IPO at the full $18.00 offer, per its Schedule 13D. It paid the same price as every other IPO buyer.
What is the next AKTS catalyst?
Phase 1 data for [225Ac]Ac-AKY-1189, expected Q1 2027 per BioPharma Dive, with NECTINIUM-2’s primary completion estimated December 2027. Before that, BActinium-1 (B7-H3) dose-escalation updates following the ASCO imaging presentation in May.
Sources
First-hand (filings and registry):
- Aktis Announces Pricing of its Upsized IPO (17,650,000 shares at $18.00) — Aktis Oncology, 2026-01-08
- Aktis S-1/A, January 5, 2026 (11,775,000 shares at $16–18) — SEC EDGAR
- Aktis S-1/A, January 7, 2026 (upsize to 17,650,000 shares) — SEC EDGAR
- Aktis 424B4 final prospectus (pipeline; Lilly collaboration terms; syndicate allocations) — SEC EDGAR
- Aktis Q2 2026 10-Q (full greenshoe; net $334.4M; cash $517.3M; runway into 2029) — SEC EDGAR
- Eli Lilly Schedule 13D (5,555,555 IPO shares ≈ $100M; 11.9% post-IPO) — SEC EDGAR
- MPM entities Schedule 13D (1,112,777 IPO shares ≈ $20.0M) and Vida Ventures Schedule 13D (812,455 IPO shares) — SEC EDGAR
- Q2 2026 results 8-K (first-in-human AKY-2519 imaging/dosimetry data) — SEC EDGAR
- ClinicalTrials.gov: NCT07020117 (NECTINIUM-2) · NCT07581184 (BActinium-1)
Aftermarket and context:
- The New Biotech IPO Class: Bigger, Later-Stage, and Judged Harder — Pharma Daily (parent analysis; class table and median)
- Aktis raises $318M in 2026’s first biotech IPO — BioPharma Dive, 2026-01-08
Provenance: collected 2026-09-05. Filing figures from the EDGAR documents above. Prices: debut detail (open $27.00 / close $22.40 on January 9) via the stock_finance_data feed; the Mar 27 close ($15.19), Jun 30 close ($32.23), Aug 28 close ($25.78), and Sep 4 close ($27.05) via the Yahoo Finance daily series for AKTS. Percentages vs the $18.00 offer are computed from those closes. “Highest close” and “lowest close” refer to closing prices, not intraday extremes. All performance figures are marked to the September 4, 2026 close and will move with the market.