Latigo Biotherapeutics priced an upsized IPO at the top of its range on August 6, 2026 — 19,200,000 shares at $18.00 for $345.6 million gross, $397.4M after the underwriters exercised the full 2.88M-share greenshoe — and closed its first session on August 7 up just 1.4%. As of the September 4 close the stock trades at $23.04, +28.0% versus offer, with most of that gain arriving in a six-session late-August climb on no disclosed company catalyst.
TL;DR — Latigo (Nasdaq: LTGO — the class table left the ticker unverified; confirmed here from the 424B4 cover) is a single-mechanism pain company: LTG-001 (onzotrigine), an oral selective NaV1.8 inhibitor with a completed 343-patient Phase 2 in postoperative pain and an FDA agreement that the trial counts as one of two pivotal trials. Net proceeds were ~$363.9M per the Q2 10-Q; runway guided into 2029. The tape: +1.4% debut, highest close $25.00 on August 27, +28.0% as of the September 4 close. Caveat: neither Phase 3 trial (bunionectomy, open-label safety) was registered on ClinicalTrials.gov as of September 5 — initiation is guided for 2H 2026 but not yet visible in the registry.
This is a per-company companion to our 2026 IPO class deep-dive, which found the aftermarket rewarding late-stage single-asset stories and punishing platform narratives. Latigo is a clean test of that finding: one mechanism, one lead asset, one FDA-blessed pivotal path.
The asset: onzotrigine, a Phase 2 already counted toward registration
LTG-001 — INN onzotrigine — is an oral selective NaV1.8 inhibitor for moderate-to-severe acute pain, including postoperative pain, dosed as needed for up to 30 days; an IV formulation is also in development. The pivotal-track evidence is the abdominoplasty Phase 2 (NCT07102459, N=343, completed January 2026): the high dose (450 mg loading, 300 mg q12h) delivered SPID48 of 62.1 points versus placebo (p<0.001), numerically exceeding the trial’s hydrocodone/APAP active comparator — whose improvement versus placebo was 40.9 points (p=0.001); median time to a ≥2-point pain reduction was 52 minutes against 83 minutes for the opioid; and 52.3% of high-dose patients stayed opioid-free over 48 hours versus 22.1% on placebo (p<0.001). FDA agreed the abdominoplasty trial may serve as one of two pivotal trials; the plan is a placebo-controlled bunionectomy trial plus an open-label safety trial, both initiating 2H 2026, topline 2H 2027, then an NDA. The data were published in the New England Journal of Medicine on July 29, 2026 — pre-IPO, and per the company only the second original acute-pain drug research paper in NEJM in 15 years.
The origin is an in-license: Latigo took a worldwide exclusive, royalty-bearing license to the NaV1.8 patents from the Lieber Institute for Brain Development in July 2020. The 424B4 splits the payment schedule by product class: for a Sole Product, Latigo would owe up to $48.5M in development and regulatory milestones on the first product, $23.75M on each subsequent one, up to $95M in sales milestones, and tiered low-to-mid single-digit royalties. But Latigo has concluded LTG-001 is a Joint Product, and for the first joint product the obligations are far lighter: up to $4.0M in regulatory milestones, up to $9.5M in sales milestones, a low-single-digit royalty, and no milestone obligations on subsequent joint products. Behind LTG-001 sit LTG-321, a structurally distinct next-gen oral NaV1.8 in a Phase 2 osteoarthritis-of-the-knee crossover trial (~120 patients, topline 2H 2027), and LTG-418 at preclinical stage. The company — founded November 2018, headquartered in Thousand Oaks, run by CEO Nima Farzan with CMO Neil Singla — raised ~$321.5M privately, including a $150M Series B at $10.1050 per share.
The deal: 20% upsized at the top, full shoe, and real crossover buying
| Step | Shares | Price | Gross |
|---|---|---|---|
| S-1 (Jul 17) | blanks | — | — |
| Marketed range (S-1/A, Aug 3) | 16,000,000 | $16–18 | $256–288M |
| Priced (Aug 6) — top of range, +20% via Rule 462(b) | 19,200,000 | $18.00 | $345.6M |
| Greenshoe exercised in full (per Q2 10-Q) | 22,080,000 | $18.00 | $397.4M |
Table 1: Latigo pricing steps per the S-1, the S-1/A, the pricing release, and the Q2 2026 10-Q. Net proceeds ~$363.9M are the 10-Q actual, not the prospectus estimate ($315.7M ex-greenshoe).
Two corrections to the parent class table: the raise was $345.6M at pricing, but the final figure after the full greenshoe is $397.4M gross / ~$363.9M net; and the first-day return was +1.4% on the close ($18.25), not +1.0% — some outlets quoted “+17%”, which confuses the $21.00 opening print with the close. At $397.4M, the deal is 1.35x the class median of $295M. The syndicate — Goldman Sachs, Jefferies, Leerink Partners, Guggenheim — placed the deal without any cornerstone or anchor-investor language in the 424B4, and market cap at pricing was roughly $1.14B.
The post-IPO 13D/13G filings show the buying was real, not just indicated: RA Capital reported 5,295,690 shares (8.4%), Deep Track Capital 4,445,656 shares (7.03% — up ~1.95M from its 2,496,656-share pre-IPO position per the 424B4; our subtraction, as the 13G states no pre-IPO figure), and Access Industries / AI Biotechnology 3,185,177 shares (5.0%). One flag on reading the register: Foresite Capital’s 14.5% 13D is a conversion of pre-IPO preferred stock, not new IPO buying — the same distinction that mattered in the Hemab register. Pre-IPO, Westlake BioPartners held 29.9%, Foresite 20.5%, and 5AM Ventures 16.6%.
The tape: a flat debut, then a run with no news behind it
LTGO’s debut was the weakest part of the story: a $21.00 open faded to an $18.25 close (+1.4% versus the $18.00 offer), and the stock drifted near offer through August 10–11 ($18.56, then $18.52). Then it climbed for over two weeks — $19.38 on August 12 to a $24.23 close on August 28 (+34.6% versus offer, confirming the class table’s figure) — peaking at the highest close of $25.00 on August 27 (+38.9%; intraday high $25.93). We find no company-specific dated catalyst for the August 17–27 leg ($19.30 to $25.00, +29.5%): the NEJM publication was July 29, pre-IPO, and no clinical-data or designation 8-Ks were filed between the IPO and September 5. After an August 31 pullback to $22.02, the September 3 Q2 print — full greenshoe confirmed, runway extended into 2029, and an ex-FDA anesthesia/pain division deputy director hired as SVP Regulatory Affairs — was followed by closes of $22.48 and $23.04 on September 3 and 4.
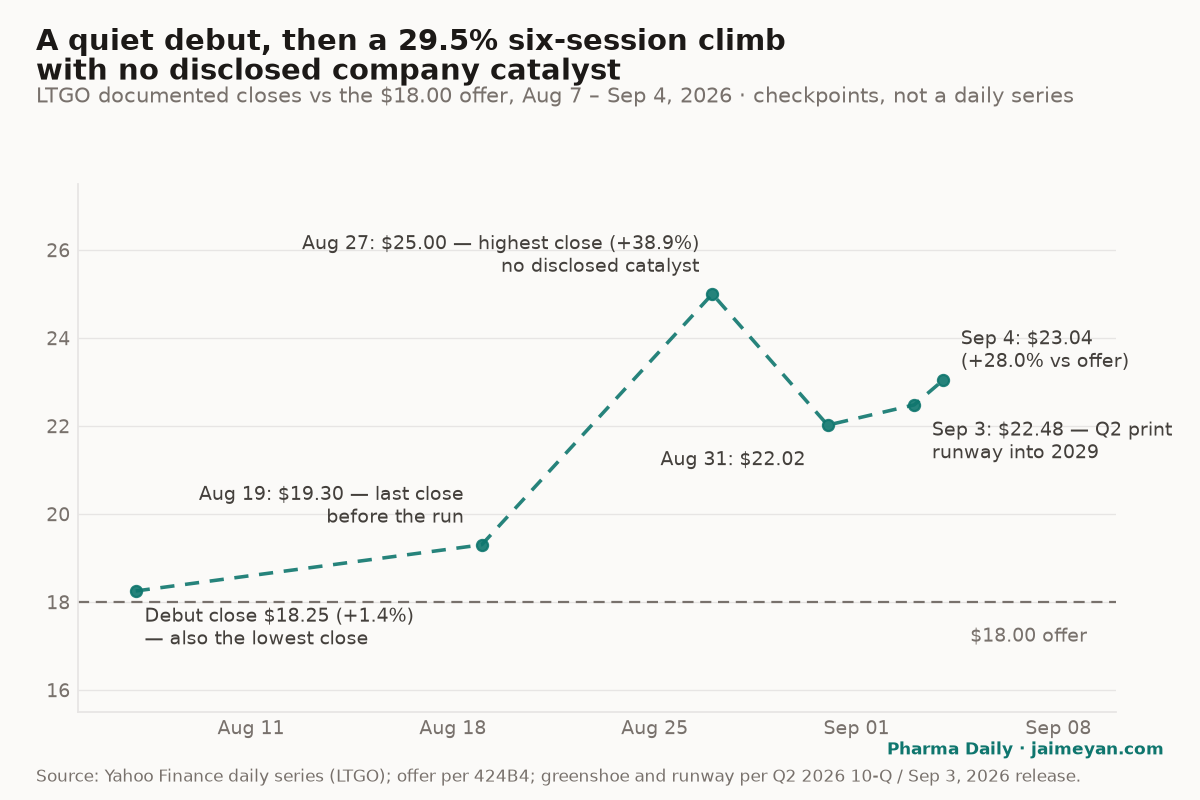
Figure 1: LTGO’s re-rate came between disclosures, not on them — the steepest leg (August 19–27) has no matching company filing. Documented closes per the Yahoo Finance daily series; dashed segments connect documented checkpoints, not a daily series.
Against the class bifurcation: Latigo is a confirmation. A Phase 3-ready single asset with an FDA-counted pivotal and a dated topline is exactly the profile the 2026 tape has paid for — the same profile that carried Veradermics — while platform stories like Eikon priced below offer. What is unusual here is the shape: the market did not wait for a post-IPO catalyst to re-rate the name.
What would change the story
- Phase 3 initiation, guided 2H 2026 — the bunionectomy pivotal and the open-label safety trial were not registered on ClinicalTrials.gov as of September 5, 2026. Registration is the verifiable start signal; a slip into 2027 pushes the NDA with it.
- Phase 3 topline, 2H 2027 — the binary: whether bunionectomy replicates the abdominoplasty SPID48 and opioid-sparing result at registrational scale.
- LTG-321 Phase 2 OA-knee topline, 2H 2027 — the life-cycle asset; the cited sources disclose no trial-site locations, so watch both ClinicalTrials.gov and the EU registry for registration.
- The NaV1.8 race — BioPharma Dive framed the deal as Latigo’s entry in the non-opioid ion-channel pain race against Vertex and Lilly; competitor readouts move this tape even when Latigo files nothing.
- Financing discipline — runway is guided into 2029 against both 2H 2027 readouts; a raise before topline would contradict it.
One Take
Latigo is the class bifurcation working as advertised — a Phase 3-ready single asset priced at the top of its range, upsized, and re-rated — but the interesting detail is when the tape paid: the sharpest leg of the rally had no company disclosure behind it, which says the market is pricing the pivotal path as de-risked on the strength of the FDA agreement and the NEJM-published Phase 2, not waiting for new data. I read that as a reasonable mark, not froth: SPID48 separation against both placebo and an opioid comparator, 52-minute onset, and half the patients opioid-free is a Phase 3 hypothesis with unusually specific falsifiers. My conviction is moderate that LTGO holds its premium into the readouts, because the raise funds both 2H 2027 toplines with runway into 2029 and the register shows crossover funds adding, not flipping. What would change my mind: the Phase 3 programs failing to appear in the registry by early 2027, a bunionectomy design that softens the placebo control, or a financing before topline — any of the three would tell you management prices the risk higher than the tape does.
Key takeaways
- Latigo priced 19.2M shares at the $18.00 top of range on August 6 (upsized 20% via Rule 462(b)); the full greenshoe took the deal to $397.4M gross — 1.35x the $295M class median — with ~$363.9M net per the Q2 10-Q.
- The stock closed its debut at +1.4% (not the “+17%” some outlets quoted from the $21.00 open), hit its highest close at $25.00 on August 27, and stands +28.0% versus offer as of the September 4 close.
- The entire late-August climb (+29.5% from August 17 to 27) occurred with no company filing — the NEJM abdominoplasty paper landed July 29, pre-IPO.
- LTG-001 (onzotrigine) is an oral selective NaV1.8 inhibitor whose Phase 2 already counts as one of two pivotal trials per FDA; bunionectomy and safety trials start 2H 2026, topline 2H 2027, runway into 2029 covers both.
- No anchor or cornerstone was disclosed, but 13D/13G filings confirm actual post-IPO buying by RA Capital (8.4%), Deep Track (7.03%), and Access Industries (5.0%); Foresite’s 14.5% is preferred conversion, not new money.
FAQ
Did Latigo’s IPO have anchor investors?
No. The 424B4 contains no cornerstone or anchor-indication language. Post-IPO 13D/13G filings show RA Capital, Deep Track, and Access Industries holding 5–8.4% stakes, but those are disclosed positions after the fact, not pre-committed anchors.
Why did LTGO rally in late August with no news?
There is no documented company catalyst between the August 10 closing 8-K and the September 3 results 8-K. The August 19–27 climb to a $25.00 close followed the pre-IPO NEJM publication (July 29) and trade-press framing of Latigo as a lead contender in the non-opioid pain race; we report the move as data and note the absence of a matching filing.
What is onzotrigine’s path to approval?
FDA agreed the completed 343-patient abdominoplasty Phase 2 can serve as one of two pivotal trials. Latigo plans a placebo-controlled bunionectomy trial and an open-label safety trial starting 2H 2026, topline 2H 2027, then an NDA — funded by the IPO proceeds with runway guided into 2029.
Sources
First-hand (filings, releases, registry):
- Latigo 424B4 final prospectus (pipeline, LIBD license, principal stockholders, no cornerstone language) — SEC EDGAR, 2026-08-07
- Latigo Announces Pricing of Upsized $345.6M IPO (19.2M shares at $18.00) — GlobeNewswire, 2026-08-07
- S-1, July 17, 2026 · S-1/A, August 3, 2026 (16M shares at $16–18) · Rule 462(b) S-1MEF, August 6, 2026 (upsize to 19.2M) — SEC EDGAR
- 8-K, August 10, 2026 (IPO closing) and 8-K, September 3, 2026 (Q2 results; full greenshoe; NEJM; regulatory hire) with Exhibit 99.1 — SEC EDGAR
- Latigo Q2 2026 10-Q (net proceeds ~$363.9M; cash $55.0M at June 30; runway into 2029) — SEC EDGAR
- 13D/13G: RA Capital (8.4%) · Deep Track Capital (7.03%) · Access Industries / AI Biotechnology (5.0%) · Foresite Capital (14.5%, preferred conversion) — SEC EDGAR
- NEJM publication announcement (July 29, 2026) — Latigo Biotherapeutics (live page removed; archived copy)
- ClinicalTrials.gov: NCT07102459 (abdominoplasty Phase 2) · NCT06774625 (third-molar Phase 2) · NCT07110610 (LTG-321 Phase 1) · sponsor listing (no Phase 3 registered as of September 5, 2026)
Aftermarket and context:
- The New Biotech IPO Class: Bigger, Later-Stage, and Judged Harder — Pharma Daily (parent analysis; class table and $295M median)
- Latigo IPO raises nearly $350M for pain drug development — BioPharma Dive, 2026-08-07
Provenance: collected 2026-09-05. Filing figures from the EDGAR documents above; prices (debut close $18.25; Aug 17 $19.30; Aug 19 $20.94; Aug 27 $25.00; Aug 28 $24.23; Aug 31 $22.02; Sep 3 $22.48; Sep 4 $23.04) via the Yahoo Finance daily series for LTGO. Percentages versus the $18.00 offer are computed from those closes; “highest/lowest close” refer to closing prices, not intraday extremes. The abdominoplasty enrollment figure (N=343) is the company-reported actual in the 424B4; the registry listing matches it. Event dates above are the dates of the underlying events; where a filing date differs (e.g., the September 3 8-K reporting second-quarter results), the 8-K was filed the same day. All performance figures are marked to the September 4, 2026 close and will move with the market.