Hemab Therapeutics priced an upsized IPO at the top of its range on April 30, 2026 — 16,750,000 shares at $18.00, a 42% build from its first amended filing — and closed its first session up 88.9% at $34.00. As of the September 4 close the stock trades at $44.41, +146.7% versus offer — among the class’s top three marks.
TL;DR — Hemab (Nasdaq: COAG) raised $301.5M at pricing and $346.7M with the greenshoe, exercised in full (net $317.2M) — 3.5x the $100M placeholder on its April 10 S-1. No anchor investors were disclosed; the book was built the plain way. The post-IPO climb is entirely data-stamped: ISTH presentations (+13.5% on June 29), the July 14 sutacimig long-term data (+9.6% that day), and an August 11 Q2 update disclosing HMB-002’s Phase 1/2 bleed-elimination data and FDA’s endorsement of the Glanzmann Phase 3 package. Cash of $457.5M at June 30 funds operations into 2029. Performance figures are marked to the September 4 close; prices move daily. Caveat: the lead indications are tiny (~10,000 Glanzmann + Factor VII–deficiency patients in target geographies), so the current mark prices pipeline breadth — the “Hemab 2x3 by 2030” plan — as much as the lead program.
This is a per-company companion to our 2026 IPO class deep-dive. Hemab is the useful contrast case to Kailera: both companies are built on in-licensed molecules, and the tape treated them oppositely.
The asset: sutacimig, a Novo Nordisk bispecific Hemab is developing itself
The lead is sutacimig (HMB-001), a bispecific antibody (Genmab’s DuoBody format, in-licensed; the TLT-1×Factor VII bispecific patents are exclusively licensed from Novo Nordisk) that recruits Factor VII to activated platelets via TLT-1. It is a weekly subcutaneous prophylactic for Glanzmann thrombasthenia (Phase 1/2, NCT06211634) and Factor VII deficiency (Phase 2, NCT07347249). The data behind the IPO: 34 patients treated, 31 efficacy-evaluable at the October 14, 2025 cutoff; mean annualized treated bleed rate reductions of 19–87% across regimens, a 100% reduction in mean high-intensity ATBR, and 92% of patients with at least one run-in bleed showing improvement. The designation stack is full: FDA Breakthrough Therapy (granted March 5, 2026), Fast Track, FDA and EMA orphan drug, and UK MHRA ILAP — all in GT.
The difference from the Hengrui model matters for how the tape read this deal: Hemab in-licensed the molecule but ran its own trials — the Phase 1/2 is Hemab’s, started December 2022. The licensor relationship is pedigree, not dependency: Novo Holdings also held 15.2% pre-IPO.
Two more programs widen the franchise. HMB-002 (monovalent antibody raising endogenous VWF and FVIII) is in the Velora Pioneer Phase 1/2 in von Willebrand disease (NCT06754852, registry-estimated enrollment ~108); the August 11 update disclosed a ≥2.4-fold peak VWF/FVIII increase and zero treated bleeds in the 28 days post-dose in 8 of 9 evaluable patients (mean ATBR 1.6 versus a 20.1 baseline), with Part B data guided for late 2026/early 2027. HMB-003, a long-acting plasmin inhibitor for heavy menstrual bleeding, was unveiled in July 2026; its first-in-human Phase 1 (NCT07798505) is planned for 2H 2026 — the registry lists an estimated August 17 start and “not yet recruiting” status as of September 5 — with initial data guided mid-2027. Management’s roadmap: “Hemab 2x3 by 2030” — two commercial medicines, two late-stage, two early-stage programs.
Pre-IPO the company raised ~$346M since inception per the 424B4 — including a $135.2M Series B in 2023 and a $156.9M Series C in October 2025 — from a crossover-heavy register: RA Capital 17.6%, Novo Holdings 15.2%, AI DEN-MAB 13.8%, Sofinnova 8.7%, Deep Track 8.0%, SMALLCAP World Fund 7.9%.
The deal: 42% upsized in three days, no anchors disclosed
| Step | Shares | Price | Gross |
|---|---|---|---|
| Initial S-1 (Apr 10) | $100M placeholder | — | — |
| S-1/A (Apr 27) | 11,764,706 | $16–18 | $188–212M |
| Upsized S-1/A (Apr 28–30) | 15,000,000 → 16,750,000 | $16–18 | up to $301.5M |
| Greenshoe exercised in full (closed May 4) | 19,262,500 | $18.00 | $346.7M |
Table 1: Hemab pricing steps per the S-1 (placeholder; Renaissance Capital), the S-1/A filings (Apr 27: 11,764,706 shares; Apr 30: 15,000,000), the pricing release, the closing release, and the Q2 10-Q (net $317.2M).
The 424B4 discloses no anchor or cornerstone indications — unlike Aktis (Lilly in-book) or Kailera (insider indications). The syndicate (Goldman Sachs, Jefferies, Evercore ISI; Wedbush PacGrow as lead manager) upsized the deal twice in three days on the strength of the crossover register the company already had. At $346.7M with the shoe, the deal is 1.18x the class median.
The tape: every leg came with a data print
COAG opened May 1 at $27.00 and closed at $34.00 (+88.9%), then gave back a quarter of it: $24.98 by June 12, the lowest close since the debut. The recovery is fully annotated by disclosures: the late-June ISTH presentation announcement (+13.5% to $36.73 on June 29), the July 14 ISTH data — sustained bleed reduction in the GT long-term extension and preclinical thrombin-generation restoration across 88% of FVII variants (+9.6% to $43.31, then $49.29 by July 17) — and the August 11 Q2 update with the HMB-002 bleed data and FDA’s endorsement of the sutacimig Phase 3 package. The closing high is $54.94 (August 14); the stock has since eased to $44.41.
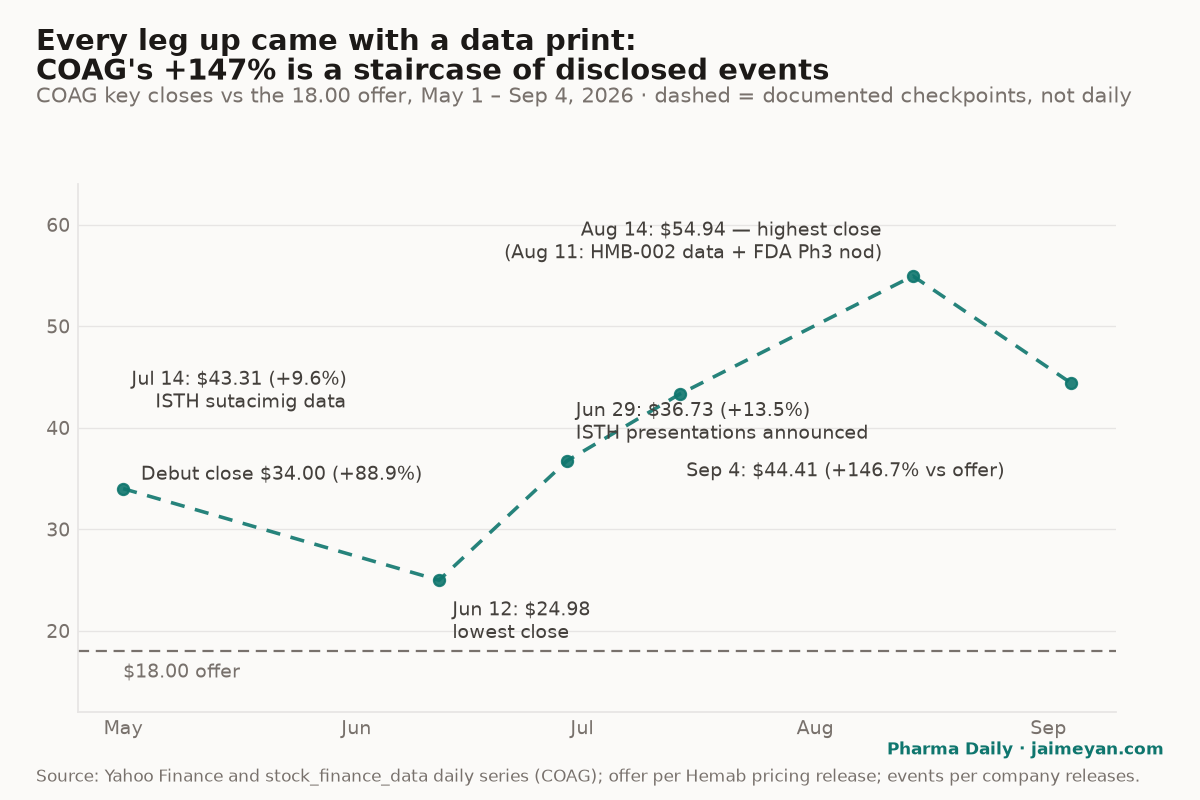
Figure 1: COAG’s +147% is a staircase of disclosed events — ISTH, the July data, the August FDA/Phase 3 update — with a five-week give-back after the debut. Documented closes per the Yahoo Finance and stock_finance_data series; dashed segments connect documented checkpoints, not a daily series.
Against the class bifurcation: Hemab is the template the tape rewards — one franchise, human data in hand, a regulator-endorsed pivotal path — with two qualifiers. The register was crossover insiders, not a strategic anchor. And the markets are small: ~10,000 GT+FVIID patients and ~120,000 VWD patients in target geographies. A +147% mark on that base is paying for the multi-product plan, not the lead indication alone.
What would change the story
- The GT Phase 3 start, guided 2H 2026 — FDA has endorsed the package; the posted protocol and first patient are the next hard markers.
- FVIID Phase 2 data, late 2026/early 2027 (NCT07347249).
- HMB-002 Part B, late 2026/early 2027 — whether the zero-bleed signal holds at the 150 mg cohort.
- HMB-003 first-in-human data, mid-2027 — the first read on whether the franchise extends beyond antibody prophylaxis.
One Take
Hemab is my favorite counterfactual in this class because it isolates the variable Kailera can’t: origin of evidence. Both are single-franchise companies built on in-licensed molecules; Hemab’s data are self-generated, its licensor is a shareholder-pedigree rather than a data dependency, and its regulator has already blessed the pivotal package — the tape pays +147% for that combination while charging Kailera a round-trip for the opposite. I do note the tension nobody prices: the lead markets are ~10,000 patients, so today’s valuation already capitalizes the 2x3 expansion plan, which means HMB-002 and HMB-003 readouts now carry index weight on a stock that was bought as a GT story. Conviction: moderate that COAG’s mark tracks the Phase 3 start and the FVIID/HMB-002 readouts rather than class flow — the post-peak drift from $54.94 to $44.41 is digestion on no news, not a verdict change. Falsifiers: the GT Phase 3 not started by year-end, a Part B slip on HMB-002, or insider selling accelerating from the crossover register that owns the majority of the pre-IPO cap table.
Key takeaways
- Hemab upsized 42% in three days and priced at the $18 top of range on April 30: $301.5M at pricing, $346.7M with the full greenshoe (net $317.2M) — 3.5x its April 10 placeholder, with no disclosed anchors.
- The +88.9% debut and +146.7% mark (September 4) decompose into dated disclosures: ISTH (June 26/July 14) and the August 11 Q2 update with HMB-002’s zero-bleed data and FDA’s Phase 3 endorsement.
- Sutacimig is in-licensed (Novo Nordisk patents, Genmab DuoBody) but self-developed clinically — the structural opposite of the Hengrui model, and the tape priced the difference.
- The pipeline bet is breadth: HMB-002 (VWD) and HMB-003 (heavy menstrual bleeding) read out late 2026 through mid-2027, against a “2x3 by 2030” plan.
- Cash of $457.5M at June 30 with runway into 2029 covers the Phase 3 start; Q2 R&D was $20.3M against a $24.2M net loss.
FAQ
Is Hemab a Novo Nordisk spinout?
No. Hemab holds an exclusive worldwide license to Novo Nordisk’s TLT-1×FVII bispecific patents and a Genmab DuoBody platform license, and Novo Holdings owned 15.2% pre-IPO — but the company is an independent Delaware holdco over Hemab ApS (Copenhagen), and the sutacimig clinical program is Hemab-run.
What drove the stock from $34 to $55?
Three disclosed events: the June 26 ISTH announcement (+13.5%), the July 14 ISTH sutacimig data (+9.6%), and the August 11 Q2 update (HMB-002 data; FDA endorsement of the GT Phase 3 package). The closing high was $54.94 on August 14; the stock has since eased to $44.41 on no new adverse disclosure.
What is the next catalyst?
The Glanzmann Phase 3 start, guided for 2H 2026 with FDA’s endorsement in hand, then Factor VII-deficiency Phase 2 data and HMB-002 Part B, both guided late 2026/early 2027.
Sources
First-hand (filings, releases, registry):
- Hemab Announces Pricing of Upsized IPO (16,750,000 shares at $18.00) — GlobeNewswire, 2026-04-30
- Hemab Announces Closing and Full Exercise of Underwriters’ Option (19,262,500 shares; ~$346.7M) — GlobeNewswire, 2026-05-04
- Hemab S-1, April 10, 2026 and S-1/A, April 28, 2026 (upsize) — SEC EDGAR
- Hemab 424B4 final prospectus (pipeline; licenses; designations; principal stockholders) — SEC EDGAR
- Hemab Q2 2026 10-Q (net $317.2M; cash $457.5M; runway into 2029) — SEC EDGAR
- Q2 2026 results release (HMB-002 data; FDA Phase 3 endorsement; HMB-003 unveil) — SEC EDGAR
- ISTH 2026 sutacimig data release, July 14, 2026 — GlobeNewswire
- FDA Breakthrough Therapy Designation for sutacimig in GT (March 5, 2026) — Hemab Therapeutics
- ClinicalTrials.gov: NCT06211634 (sutacimig GT) · NCT07347249 (sutacimig FVIID) · NCT06754852 (HMB-002 VWD) · NCT07798505 (HMB-003)
Aftermarket and context:
- The New Biotech IPO Class: Bigger, Later-Stage, and Judged Harder — Pharma Daily (parent analysis; class table and median)
- Two biotechs raise a combined $556M in latest spurt of IPOs — BioPharma Dive, 2026-04-30
- After IPO success, Hemab’s CEO seeks the flavor of a multi-product coagulation company — Fierce Biotech, 2026-08-13
- Hemab files for a $100M IPO — Renaissance Capital, April 2026
Provenance: collected 2026-09-05. Filing figures from the EDGAR documents and releases above; prices (debut open $27.00 / close $34.00; Jun 12 low close $24.98; Jun 29 $36.73; Jul 14 $43.31; Jul 17 $49.29; Aug 14 $54.94; Aug 28 $44.84; Sep 4 $44.41) via the Yahoo Finance daily series and the stock_finance_data feed for COAG. Percentages vs the $18.00 offer are computed from those closes; “highest/lowest close” refer to closing prices, not intraday extremes. No anchor-investor disclosure exists in the 424B4; we say so rather than infer. All performance figures are marked to the September 4, 2026 close and will move with the market.