Vogenx priced the smallest IPO of the 2026 biotech class on August 11 — 6,250,000 shares at $13.00 for $81.25M gross — and closed its first session flat at the offer price. Then, with no clinical data, no earnings, and no management change, the stock climbed to a highest close of $34.00 on August 31; as of the September 4 close it sits at $31.73, +144.1% versus offer.
TL;DR — Vogenx (Nasdaq: VOGX — the class table left the ticker unverified; confirmed here from the 424B4 cover) raised $81.25M at the top of an $11–13 range, non-upsized, with the 15% greenshoe fully exercised at the August 19 close for a final gross of ~$93.4M — a correction to the parent table’s $81.3M, which was accurate at pricing but stale once the shoe closed. The asset is mizagliflozin, an oral selective SGLT1 inhibitor in-licensed from Kissei, with two small completed Phase 2s in post-bariatric hypoglycemia and a Phase 2b (EMERGE, 36 patients planned per the registry) not yet recruiting, topline targeted 2027. The entire post-IPO run happened on zero company disclosures — no clinical-data, earnings, or management 8-K was filed in the window; the only dated corporate filings were an August 13 charter/bylaws 8-K and the August 19 greenshoe close. All performance figures are marked to the September 4, 2026 close; prices move daily.
This is a per-company companion to our 2026 IPO class deep-dive, which found the aftermarket rewarding late-stage single-asset stories and punishing platform narratives. Vogenx stress-tests that finding at the smallest scale in the class: it is single-asset but not late-stage, and its re-rate was earned on nothing a filing can point to.
The asset: one SGLT1 inhibitor, in-licensed, with a subgroup story
Mizagliflozin is an oral, minimally absorbed, selective inhibitor of SGLT1, the intestinal glucose transporter. Vogenx did not discover it: the molecule was in-licensed from Kissei Pharmaceutical in December 2021 (amended September 2023), exclusive worldwide excluding Japan, Korea, and Taiwan, for $1.0M upfront, up to $27.0M in development and regulatory milestones, and a high-single-digit royalty on net sales. More than 500 subjects have been exposed across 10 clinical studies, including Kissei-run trials in healthy volunteers, type 2 diabetes, and chronic idiopathic constipation.
The lead indication is post-bariatric hypoglycemia (PBH) — an estimated 450,000-plus US patients with no FDA-approved therapy. The evidence base at IPO was two small completed Phase 2s. VGX-001-011 (NCT05541939, single-dose, 9 enrolled, completed February 2023): in the subgroup hypoglycemic at baseline, glucose nadir rose +19.3 mg/dL (+38%, p=0.03) and insulin peak fell −53% (p=0.016) versus baseline. VGX-001-012 (NCT05721729, repeat-dose crossover, 15 enrolled, completed May 2024): in the hypoglycemic-at-baseline subgroup, 5+10 mg TID versus placebo lifted glucose nadir +56% (p=0.028) and cut glucose peak −34% (p=0.031) and insulin peak −64% (p=0.03). Read the all-patient rows before the subgroup rows: in the full 15-patient population the nadir effect lost significance (+17%, p=0.19). The drug’s effect concentrates in patients who are actually hypoglycemic at baseline — which is presumably how EMERGE will be enrolled.
The next trial is EMERGE, a Phase 2b of 5 mg and 10 mg TID versus placebo with a primary endpoint compositing Level 2/Level 3 hypoglycemic events. The registry record (NCT07760961) lists 36 planned — a registry estimate, not a company-reported actual — with a start date of October 2026 and primary completion October 2027; the 424B4 guides topline in 2027, followed by an End-of-Phase-2 FDA meeting and a Phase 3. Behind PBH: a gastroparesis Phase 2 proof-of-concept planned to initiate in 2027 (a market the prospectus sizes at over 5M US patients, with only black-boxed metoclopramide approved), a GIP-dependent Cushing’s syndrome IND anticipated in 2027 subject to additional funding, and preclinical VGX-2857 for weight maintenance.
The company itself is skeletal: founded 2021, headquartered in Raleigh, funded almost entirely by ~$11.5M of Series A preferred and convertible notes, with $251K of cash at March 31, 2026 and an FY2025 net loss of $1.4M. One governance flag: FY2024/FY2025 financials were restated for a net-loss-per-share calculation error.
The deal: 0.3x the class median, a sole bookrunner, and no anchors
| Step | Shares | Price | Gross |
|---|---|---|---|
| Confidential DRS (Feb 20) → public S-1 (Jul 15) | blanks | — | — |
| S-1/A (Jul 29) — terms first appear | 6,250,000 | $11–13 | $69–81M |
| Priced (Aug 11) — top of range, non-upsized | 6,250,000 | $13.00 | $81.25M |
| Greenshoe exercised in full (closed Aug 19) | 7,187,500 | $13.00 | ~$93.4M |
Table 1: Vogenx registration and pricing steps per the S-1, the July 29 S-1/A (the range and share count first appeared here, not in the August 10 amendment), the pricing release, the 424B4, and the August 19 8-K confirming the full greenshoe.
The base deal never moved: 6.25M shares at $11–13 in the first S-1/A, priced unchanged at the $13 top. Unlike Kailera or Avalyn, there was no upsizing and no bulge-bracket syndicate — JonesTrading Institutional Services ran the book alone. No anchor or cornerstone investors were disclosed in the prospectus, no post-IPO 13D or 13G is on file, and the only post-IPO Form 4s (CFO Steven Delmar, director Peter Pieraccini) report automatic convertible-note conversions at $11.70, not IPO purchases. Estimated net proceeds are ~$84.9M with the shoe per the 424B4 — an estimate, since no 10-Q has been filed. Post-shoe shares outstanding: 14,855,087, meaning the entire float sold at IPO is under half the register; pre-IPO insiders held 62.3% (33.2% post), with CEO James Green and William Wilkison at 26.5% each going in.
At ~$93.4M all-in, Vogenx is 0.3x the $295M class median — the smallest check of the 2026 class, and the last deal through before the window paused in mid-August.
The tape: +144% on zero disclosures
VOGX closed its debut (August 12) at $13.00 — 0.0%, confirming the parent table — and has never closed below offer. The run: $19.75 on August 18, $23.16 on August 19 (the greenshoe close day), $33.96 on August 28 (+161.2%, confirming the parent’s August 28 mark), a highest close of $34.00 on August 31 (+161.5%), and $31.73 at the September 4 close (+144.1%).
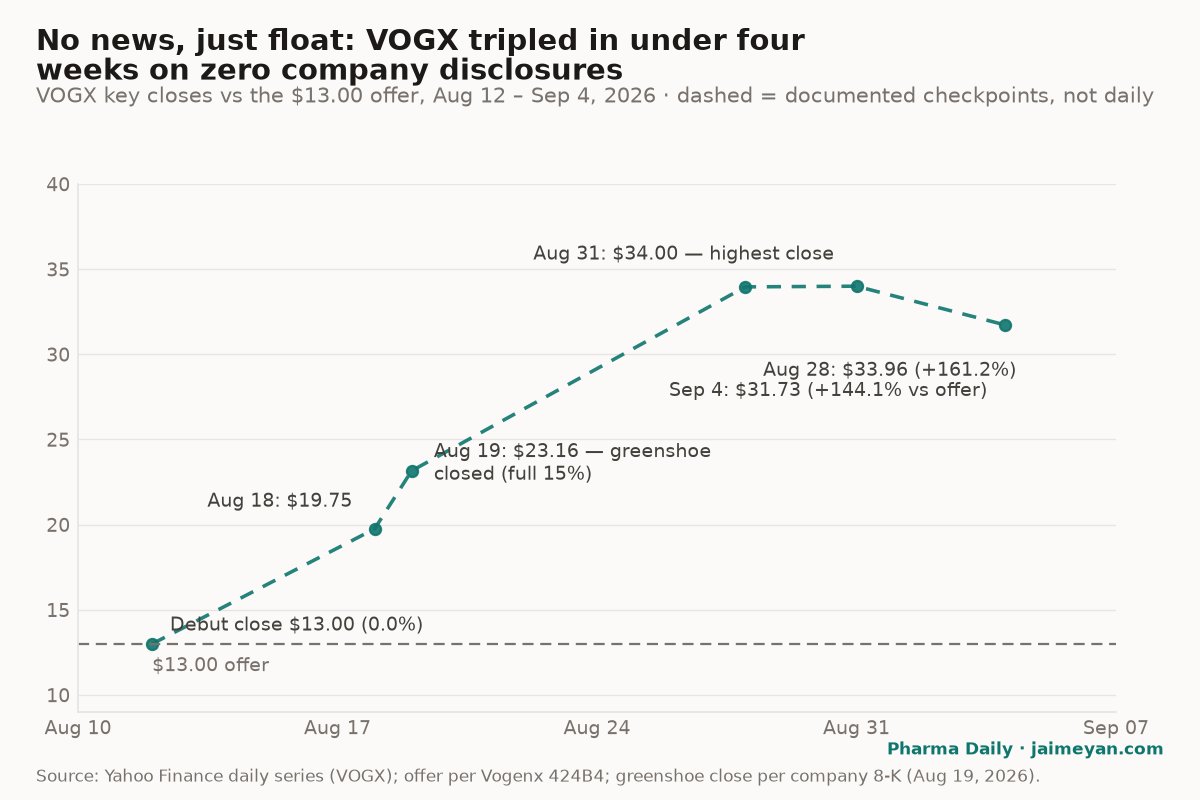
Figure 1: VOGX’s climb from August 12 to the August 31 highest close came with no clinical-data, designation, earnings, or management 8-K — the only dated corporate events in the window were the August 13 charter/bylaws 8-K and the August 19 greenshoe close. Documented closes per the Yahoo Finance daily series; dashed segments connect documented checkpoints, not a daily series.
Against the class bifurcation, direction confirms and mechanism refines. Vogenx is the opposite of the punished cohort — no platform, no discovery engine, one molecule with human data — and it was rewarded, consistent with what sank Eikon and Generate. But where Avalyn’s legs traced to dated operational disclosures, Vogenx had none: the tape here is pricing float scarcity (7.2M shares sold against a 14.9M share count) and a 2027 readout calendar, not execution. It was also the smallest deal of the July–August wave that included Braveheart Bio at $382.5M.
What would change the story
- EMERGE enrollment start (NCT07760961) — registry start is October 2026 with 36 planned; a slip past year-end pushes the 2027 topline and the whole equity case.
- First 10-Q — none has been filed since pricing; it converts the ~$84.9M net-proceeds estimate into actuals and sets the real cash runway against the through-2028 guidance.
- Any financing before 2028 — the 424B4 says IPO proceeds fund operations through 2028 but are insufficient for Phase 3; an early raise would say management marks Phase 2b-to-Phase 3 costs higher than the guide.
- Register rotation — no 13D/13G exists today; any appearance by a pre-IPO holder (Green, Wilkison, Delmar, Cheatham, Lypul, Maxim) changes the float math the rally rests on.
- Gastroparesis POC initiation in 2027 — the first test of whether this is a one-indication company.
One Take
Vogenx confirms the parent’s bifurcation finding in direction and complicates it in mechanism: the tape paid a single-asset, no-platform story, but nothing about this move was earned — no enrollment milestone, no data, no print, just a 7.2M-share float and a ticker. I would refine the finding to read: in this window, the market rewards asset focus at any stage, provided the float is small enough that price discovery is optional; the +144.1% mark (September 4 close) is a scarcity premium sitting on a 24-patient evidence base whose headline effects come from subgroups of 9 and 15. Conviction: low that the current level holds through the EMERGE readout, moderate that VOGX trades on float mechanics rather than fundamentals until enrollment data exist. Falsifiers: EMERGE failing to start screening in Q4 2026, a 13D/13G showing a pre-IPO holder distributing into the run, or a financing before the guided through-2028 runway — any of the three converts a float story into a dilution story.
Key takeaways
- Vogenx priced $81.25M (6.25M shares at $13.00, top of an unchanged $11–13 range) on August 11 and closed at ~$93.4M gross after the greenshoe was exercised in full on August 19 — 0.3x the $295M class median, the smallest deal of 2026.
- The stock: 0.0% debut, highest close $34.00 (August 31), lowest close $13.00 (August 12), +144.1% vs offer as of the September 4 close — with no post-IPO 8-K carrying clinical, earnings, or management news.
- Mizagliflozin is in-licensed from Kissei ($1.0M upfront, up to $27.0M milestones); the PBH evidence is two Phase 2s of 9 and 15 patients whose significant effects sit in hypoglycemic-at-baseline subgroups.
- The next catalyst is EMERGE (Phase 2b, 36 planned per registry, not yet recruiting): start October 2026, topline guided 2027; proceeds fund operations through 2028 but not Phase 3.
- Sole bookrunner JonesTrading, no disclosed anchors, no 13D/13G, and a 14.9M share count make this the class’s purest float-scarcity trade.
FAQ
Why is VOGX up 144% with no data readout?
There is no disclosed operational reason. Between the flat August 12 debut and the August 31 highest close, the only dated corporate filings were an August 13 charter/bylaws 8-K and the greenshoe closing on August 19 — no clinical, earnings, or management events; with 7.2M shares sold against 14.9M outstanding and no 13D/13G filers, the move is consistent with float scarcity, not new information.
Did Vogenx upsize its IPO?
No. The deal was 6,250,000 shares at $11–13 from the first S-1/A (July 29) through pricing at the $13 top on August 11 — unchanged in both size and range. The underwriters did exercise the full 15% greenshoe (937,500 shares), which closed August 19 and took total gross to ~$93.4M.
What is the next Vogenx catalyst?
EMERGE, the Phase 2b in post-bariatric hypoglycemia: the registry lists an October 2026 start and October 2027 primary completion for 36 planned patients, and the prospectus targets topline in 2027. Nothing material is scheduled before enrollment begins.
Sources
First-hand (filings, releases, registry):
- Vogenx Announces Pricing of IPO (6,250,000 shares at $13.00) — Vogenx, 2026-08-11; closing release — 2026-08-13
- Vogenx 424B4 final prospectus (Kissei license terms; Phase 2 data; EMERGE design; principal stockholders; use of proceeds; capitalization) — SEC EDGAR
- Vogenx S-1, July 15, 2026, S-1/A, July 29, 2026 (terms first appear), S-1/A, August 10, 2026 — SEC EDGAR
- 8-K, August 19, 2026 (full exercise of over-allotment; 7,187,500 shares, ~$93.4M gross) — SEC EDGAR
- 8-K, August 13, 2026 (charter/bylaws effective at closing) and post-IPO Form 4s (Delmar, Pieraccini; note conversions at $11.70) — SEC EDGAR
- Vogenx EDGAR submissions JSON (no 10-Q filed through 2026-09-05) — SEC
- ClinicalTrials.gov: NCT05541939 (Phase 2, 9 enrolled, completed) · NCT05721729 (Phase 2, 15 enrolled, completed) · NCT07760961 (EMERGE, 36 planned, not yet recruiting)
Aftermarket and context:
- The New Biotech IPO Class: Bigger, Later-Stage, and Judged Harder — Pharma Daily (parent analysis; class table and $295M median)
- Attovia, Braveheart and Vogenx seek more than $500M via IPOs — Fierce Biotech, 2026-07-30
- Renaissance Capital VOGX IPO profile
Provenance: collected 2026-09-05. Filing figures from the EDGAR documents above; closes (Aug 12 $13.00; Aug 18 $19.75; Aug 19 $23.16; Aug 28 $33.96; Aug 31 $34.00; Sep 4 $31.73) via the Yahoo Finance daily series for VOGX. Percentages versus the $13.00 offer are computed from those closes; “highest/lowest close” refer to closing prices, not intraday extremes. The EMERGE enrollment figure (36) is the registry’s planned count, not a company-reported actual. Net proceeds (~$84.9M with the full greenshoe) are the 424B4 estimate; no 10-Q has been filed. All performance figures are marked to the September 4, 2026 close and will move with the market.