Alamar Biosciences priced an upsized IPO at the top of its range on April 16, 2026 — 11,250,000 shares at $17.00 for ~$191.3M gross, $219.9M after the greenshoe was exercised in full — and closed its first session up 29.4%. As of the September 4 close the stock trades at $30.80, +81.2% versus offer.
TL;DR — Alamar (Nasdaq: ALMR) is not a therapeutics company at all: it is a commercial-stage proteomics tools business — the NULISA chemistry, the ARGO HT instrument, and consumable panels — with $74.2M of 2025 revenue, up 195% year over year. The tape has treated it as a revenue-execution story: the single biggest post-IPO move was a +30.7% one-day re-rate on the Q2 print (82% revenue growth, first FY guidance of $116–120M). Cash plus short-term investments of ~$250.1M at June 30. The overhang is legal, not clinical: the PTAB upheld all challenged claims of Olink’s US Patent 7,883,848 against Alamar in March, and Olink re-pled its infringement suit in April. Performance figures are marked to the September 4 close; prices move daily.
This is a per-company companion to our 2026 IPO class deep-dive, which found the aftermarket rewarding late-stage single-asset stories and punishing platform narratives. Alamar sits outside that split entirely — and its aftermarket suggests the bifurcation was always a therapeutics-company lens.
The asset: NULISA proteomics, $74M of real revenue, no drug pipeline
Alamar’s core technology is NULISA (NUcleic acid Linked Immuno-Sandwich Assay): antibody capture plus DNA-oligo tagging, delivering attomolar-sensitivity protein detection in blood. The commercial stack is the ARGO HT System, an automated benchtop instrument (up to 288 samples per run, launched commercially in 2024), plus consumable panels — the NGS-readout NULISAseq family (Neuro 220, Immune 340, Inflammation) and the qPCR-readout NULISAqpcr line (including an Alzheimer’s 5-plex). Focus areas are neurodegeneration, inflammation/immune, and oncology.
The numbers behind the story, per the 424B4: 2025 revenue of $74.2M, +195% versus $25.1M in 2024, more than 100 customers, average annual pull-through above $400K per instrument, and gross margin expanding from 34% to 56% across 2024–2025. The 2025 net loss was $29.8M, narrowing from $47.1M in 2024. The company was founded in May 2018 in Fremont, California; co-founder, CEO, and chairman Yuling Luo previously founded Advanced Cell Diagnostics, sold to Bio-Techne in 2016. The 424B4 balance sheet carries ~$235.0M of convertible preferred stock (aggregate liquidation preference $248.3M), anchored by a ~$128M gross Series C in February 2024, plus $56.5M of convertible notes issued in January 2026 that converted at the IPO.
There is no clinical pipeline to analyze. The only ClinicalTrials.gov record naming Alamar lists it as a collaborator — not sponsor — on NCT07646054, a Scripps-sponsored digital-lifestyle Alzheimer’s-prevention study (registry enrollment figure: 1,200; not yet recruiting). The operative risk is instead a lawsuit: on March 4, 2026 the PTAB issued a Final Written Decision upholding all challenged claims of Olink’s US Patent 7,883,848 — Alamar lost the inter partes review it had brought — and Olink re-pled its infringement suit on April 2, two weeks before the IPO priced. That overhang sits in every valuation conversation on this name.
The deal: upsized 20%, top of range, full shoe — 0.7x the class median
| Step | Shares | Price | Gross |
|---|---|---|---|
| S-1 (Mar 27) | blanks | — | — |
| S-1/A (Apr 13) — range set | 9,375,000 | $15.00–17.00 | $140.6–159.4M |
| Priced (Apr 16) — top of range, upsized ~20% | 11,250,000 | $17.00 | ~$191.3M |
| Greenshoe exercised in full (closed Apr 20) | 12,937,500 | $17.00 | ~$219.9M |
Table 1: Alamar pricing steps per the S-1, the April 13 S-1/A, the pricing release (site returns HTTP 403 to automated fetches; figures below reconcile against the 424B4 and closing 8-K), and the closing 8-K of April 20. Net proceeds were estimated at ~$198.2M with the full shoe in the 424B4 — a prospectus estimate; the Q2 10-Q does not state an actual figure. Range-row gross is computed as shares × range endpoints.
One correction to the parent table: “$220M gross” is correct only including the full over-allotment exercise; the base deal at pricing was ~$191.3M. At $219.9M with the shoe, the deal is 0.7x the $294.8M class median — below mid-pack by size, though the demand signals were strong: a ~20% share upsize between the April 13/16 amendments and pricing, and a print at the $17 top of the range.
The syndicate — J.P. Morgan, BofA Securities, TD Cowen (TD Securities (USA) LLC per the filing), Leerink Partners, and Stifel as joint book-runners — took the full 15% greenshoe, confirmed by the closing 8-K. No cornerstone investor was disclosed in the prospectus, but Sands Capital’s Schedule 13D confirms an actual IPO purchase: 300,000 shares at the $17.00 offer ($5.1M) by its Life Sciences Pulse Fund II. The pre-IPO register was already institutional: Qiming Venture Partners 18.9%, Illumina Innovation Funds 11.0%, Sherpa Healthcare Partners 8.6%, Sands Capital 7.0%, and Lian Luo 5.3% (pre-offering percentages per the 424B4). Post-IPO, Illumina, Sands, Sherpa, and Qiming have all filed 13D/13G positions.
The tape: a 30.7% one-day re-rate on the first guided quarter
A second correction to the parent table: the “+33.0% first day” figure matches only the opening print ($22.60, +32.9%). On a closing basis, ALMR’s April 17 debut was $22.00, +29.4% versus the $17 offer. The stock then spent six weeks drifting to its lowest close, $19.09 on May 26 (+12.3%), on no disclosed adverse event — even as the May 8 Q1 print showed revenue of $26.0M, +99% year over year (the session closed at $23.96, +40.9%).
The re-rate came on the Q2 print. Alamar reported on August 10 after the close: Q2 revenue of $29.4M, +82%, and the company’s first full-year guidance — FY2026 revenue of $116–120M, +59% at the midpoint. The stock went from a $27.99 close on August 10 to a $36.57 close on August 11 — +30.7% in one session, and the highest close of the post-IPO record (+115.1% vs offer). From there it consolidated: $30.71 on August 28 (+80.6%), $30.80 on September 4 (+81.2%).
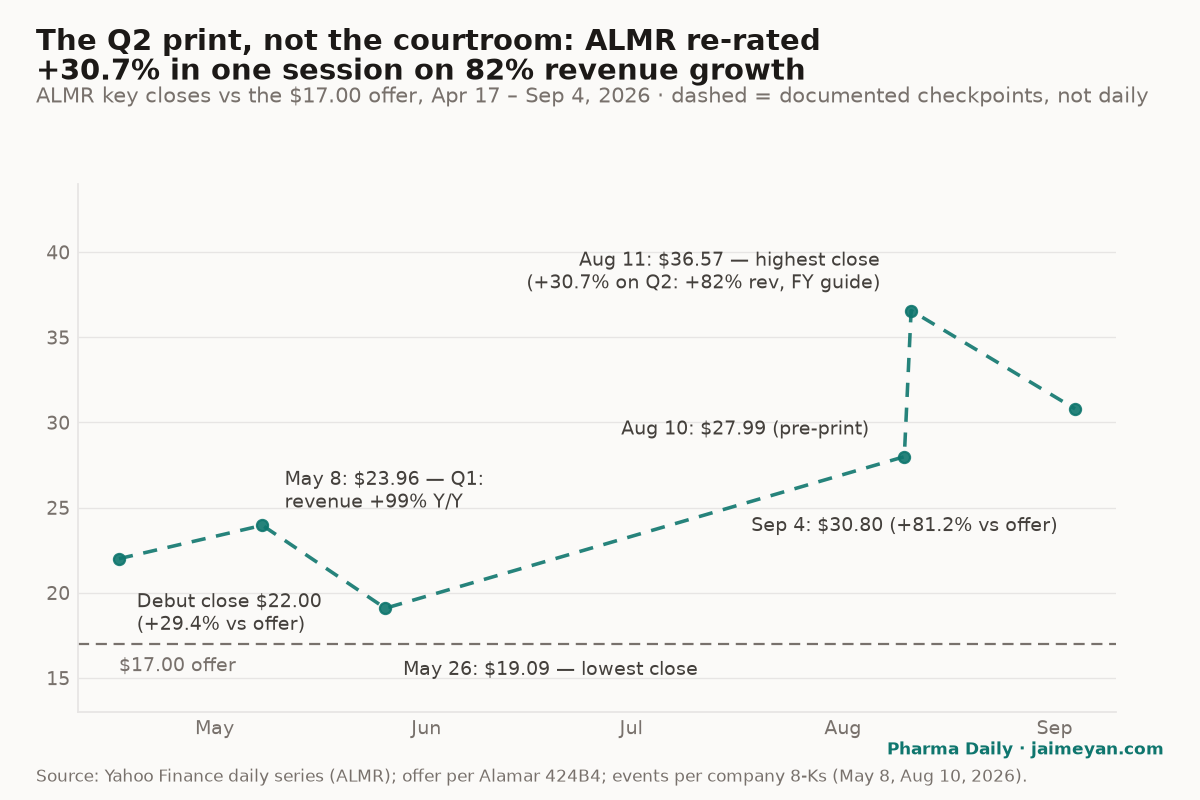
Figure 1: ALMR’s largest single-day move followed a financial disclosure — the August 10 Q2 print with first FY guidance — not any clinical event; the company has none. Documented closes per the Yahoo Finance daily series; dashed segments connect documented checkpoints, not a daily series.
Against the class bifurcation: Alamar neither confirms nor contradicts it — it escapes it. The parent’s split (late-stage single-asset rewarded, platform narratives punished, as with Eikon and Generate) presumes trial risk as the thing being priced. Here the market priced verified revenue growth instead, and paid +30.7% for it in a day. The closest functional analog in the class is Avalyn: both stocks re-rated on dated, verifiable execution disclosures rather than narratives.
What would change the story
- FY2026 guidance delivery ($116–120M, +59% at midpoint) — with no clinical calendar, the quarterly revenue print is the entire catalyst structure; the next print is the next test.
- The Olink litigation — the PTAB upheld all challenged claims of US 7,883,848 in March and Olink re-pled its infringement case in April; a district-court outcome, injunction risk, or settlement is the dominant non-operating variable.
- Gross-margin trajectory — 34% to 56% across 2024–2025; stalling here would undercut the operating-leverage half of the story.
- Register rotation — Sands added via the IPO and filed a 13D; Qiming, Illumina, and Sherpa sit on large pre-IPO positions whose 13G amendments will show who is selling into strength.
One Take
Alamar refines the bifurcation finding more than it confirms or contradicts it: the parent’s split is a therapeutics lens, and ALMR stepped outside it by not being a drug company. What the tape actually paid for here is visible revenue growing 82–99% with gross margin expanding from 34% to 56% — a tools story where the readout is a quarterly print, and the +30.7% single-day move on the first guided quarter is the cleanest evidence in the class that the 2026 market prices verified numbers over narratives. Conviction: moderate-high that ALMR trades as a revenue-execution story rather than biotech beta, because both of its post-IPO legs came on financial disclosures and it has no clinical catalysts to trade on at all. Falsifiers: revenue growth decelerating below the guided +59% FY2026 midpoint, an adverse ruling or injunction in the Olink case (the PTAB already upheld every challenged claim against Alamar), or margin stalling — any of the three converts “commercial-stage tools” back into “litigation-exposed platform,” which is exactly the profile this market has punished all year.
Key takeaways
- Alamar priced 11.25M shares at the $17 top of range on April 16 (upsized ~20%) and closed at ~$219.9M gross with the full greenshoe — 0.7x the $294.8M class median; net proceeds estimated at ~$198.2M per the 424B4 (prospectus estimate).
- The tape: +29.4% debut close, lowest close $19.09 (May 26), highest close $36.57 (August 11, the day after the Q2 print), +81.2% vs offer as of the September 4 close.
- This is a commercial-stage tools company: $74.2M 2025 revenue (+195%), Q2 2026 revenue $29.4M (+82%), first FY guidance $116–120M (+59% at midpoint), and ~$250.1M of cash plus short-term investments at June 30.
- The largest post-IPO move (+30.7% in one session) followed a financial disclosure, not a clinical event — Alamar has no drug trials; its only registry record is as a collaborator.
- The structural overhang is the Olink patent case: the PTAB upheld all challenged claims of US 7,883,848 against Alamar on March 4, 2026, and Olink re-pled its suit on April 2.
FAQ
Is Alamar a drug developer?
No. Alamar sells proteomics instruments and consumable assay panels (the ARGO HT system, NULISAseq and NULISAqpcr panels) built on its proprietary NULISA chemistry. It has no clinical drug candidates; its only ClinicalTrials.gov record is a collaborator credit on a Scripps-sponsored study.
What is the Olink litigation overhang?
Olink alleges Alamar’s technology infringes US Patent 7,883,848. Alamar challenged the patent at the PTAB and lost — the March 4, 2026 Final Written Decision upheld all challenged claims — and Olink re-pled its infringement suit on April 2, 2026, weeks before the IPO. The case is disclosed as a key risk in the 424B4; the outcome is undisclosed.
Was the greenshoe exercised?
Yes, in full. The April 20, 2026 closing 8-K confirms the underwriters exercised the entire 1,687,500-share over-allotment, taking the final deal to 12,937,500 shares and ~$219.9M gross.
Sources
First-hand (filings, releases, registry):
- Alamar Announces Pricing of Upsized IPO (11,250,000 shares at $17.00) — Alamar Biosciences, 2026-04-16
- Alamar 424B4 final prospectus (business, 2025 financials, Olink litigation, principal stockholders, use of proceeds) — SEC EDGAR
- S-1, March 27, 2026 and S-1/A, April 13, 2026 (9,375,000 shares at $15–17) — SEC EDGAR
- 8-K, April 20, 2026 (IPO closing; 12,937,500 shares; greenshoe exercised in full) — SEC EDGAR
- 8-K, May 8, 2026 (Q1 2026 results: revenue $26.0M, +99%) — SEC EDGAR
- 8-K, August 10, 2026 (Q2 2026 results) and Q2 release exhibit (revenue $29.4M, +82%; FY2026 guidance $116–120M) — SEC EDGAR
- Alamar Q2 2026 10-Q (cash $132.97M + short-term investments $117.08M; 69,392,766 shares outstanding) — SEC EDGAR
- Sands Capital Schedule 13D (300,000 IPO shares purchased at $17.00) — SEC EDGAR
- Alamar submissions JSON (13D/13G filings: Illumina, Sands, Sherpa, Qiming) — SEC EDGAR
- ClinicalTrials.gov: NCT07646054 (Alamar as collaborator; Scripps sponsor)
Aftermarket and context:
- The New Biotech IPO Class: Bigger, Later-Stage, and Judged Harder — Pharma Daily (parent analysis; class table and median)
- Alamar Biosciences files for IPO amid opening life sciences funding window — Fierce Biotech, 2026-04-14
Provenance: collected 2026-09-05. Filing figures from the EDGAR documents above; prices (debut close $22.00; May 8 $23.96; May 26 $19.09; Aug 10 $27.99 → Aug 11 $36.57; Aug 28 $30.71; Sep 4 $30.80) via the Yahoo Finance daily series for ALMR. Percentages vs the $17.00 offer are computed from those closes; “highest/lowest close” refer to closing prices, not intraday extremes. Net proceeds are the 424B4’s prospectus estimates (~$171.5M base / ~$198.2M with full shoe); no post-IPO filing states an actual figure. The NCT07646054 enrollment of 1,200 is the registry figure (study not yet recruiting). All performance figures are marked to the September 4, 2026 close and will move with the market.