On the evening of September 2, 2026, Akeso announced that ivonescimab monotherapy met the key secondary endpoint of overall survival in an interim analysis of the Phase 3 HARMONi-2 study — a statistically significant and clinically meaningful improvement over pembrolizumab monotherapy in first-line PD-L1-positive advanced NSCLC. Summit filed the readout under an 8-K the next morning. SMMT closed September 3 at $17.13, up 17.3% on the day on 2.7x its trailing-20-day volume; through the September 8 close it holds a 20.8% gain versus the pre-announcement close.
TL;DR — HARMONi-2 (AK112-303, China-only, 398 patients) is the first randomized double-blind Phase 3 to beat pembrolizumab on both endpoints it has reported: PFS at the primary analysis (HR 0.51, 95% CI 0.38–0.69; median 11.14 vs 5.82 months) and now OS at a pre-specified interim per the IDMC. The OS hazard ratio and confidence interval are undisclosed — Akeso says detailed data come at an international medical conference later this month (WCLC, per BioPharma Dive) — so the win is significance-confirmed but not yet magnitude-quantified. The tape paid anyway: SMMT +17.3% on September 3, Akeso (9926.HK) +15.3% over two sessions. Performance figures are marked to the September 8, 2026 close; prices move daily.
This is a catalyst deep-dive in the mold of our IPO class analysis, triggered by data instead of a pricing: what the readout actually showed, what the HARMONi program has accumulated around it, what the market did with the news, and which binaries price the stock from here. We first flagged the result in the September 4 daily brief.
The asset: a PD-1/VEGF bispecific with a license Summit bought for $500M
Ivonescimab (AK112 outside Summit’s territory, SMT112 inside it) is a tetravalent bispecific antibody that blocks PD-1 and VEGF in one molecule — an immunotherapy and an anti-angiogenic fused, with cooperatively enhanced binding to PD-1 in the presence of VEGF, per the company’s 8-K. Summit in-licensed it from Akeso on December 5, 2022: a $500 million upfront ($274.9 million in cash plus 10,000,000 SMMT shares, paid March 6, 2023), milestones of up to $4.555 billion ($1.05 billion regulatory, $3.505 billion commercial), and territory covering the Americas, Europe, the Middle East, Africa, and Japan — expanded in 2024 with a further $15 million payment, all per the Q2 2026 10-Q. China and the rest of Asia stay with Akeso.
HARMONi-2 (NCT05499390) is Akeso’s study: randomized, quadruple-blind, 398 patients actually enrolled, first-line locally advanced or metastatic NSCLC with PD-L1 expression (TPS ≥1%), ivonescimab monotherapy versus pembrolizumab monotherapy, run at Chinese sites from November 2022. The readout record on this trial:
| Date | Event | Result |
|---|---|---|
| May 2024 | PFS primary (interim per IDMC) | Met: median PFS 11.14 vs 5.82 months |
| Sep 2024 (WCLC 2024) | Full PFS results presented | HR 0.51 (95% CI 0.38–0.69; p<0.0001) by IRRC; later published in The Lancet |
| April 2025 | China approval (NMPA) | Marketing authorization, squamous and non-squamous |
| September 2, 2026 | OS interim (key secondary) | Met: statistically significant vs pembrolizumab; HR undisclosed |
Table 1: HARMONi-2’s reported record per Akeso’s September 2 release and Summit’s 8-K/press releases. The OS hazard ratio, confidence interval, and medians are undisclosed pending the conference presentation and journal publication.
That last row is the red-line item for this article: an OS claim must carry the trial, the comparator, and the numbers. Here the trial and comparator are disclosed and the significance ruling comes from the IDMC; the HR and CI are not yet public, and we write “undisclosed” rather than approximate one. The only quantified expectations in circulation are sell-side: UBS’s David Dai expects roughly a 24% relative reduction in the risk of death when full data are shown at WCLC, per BioPharma Dive.
The event: the fourth Phase 3 win, and the first over Keytruda on OS
Akeso’s founder and CEO Yu Xia framed the milestone in the release: this is the fourth Phase 3 study of an ivonescimab-based regimen to show statistically significant benefit on both OS and PFS. The set now reads:
- HARMONi-A — a China Phase 3 with statistically significant OS benefit, per Summit’s August 5, 2026 release (the other such study named there is HARMONi-6, below).
- HARMONi-6 (AK112-306) — ivonescimab plus chemotherapy versus tislelizumab plus chemotherapy in first-line squamous NSCLC: OS HR 0.66, a 34% reduction in the risk of death, presented May 31, 2026 and published in The Lancet.
- HARMONi-GI1 (AK112-309) — first-line advanced biliary tract cancer versus durvalumab plus chemotherapy: statistically significant OS, announced August 25, 2026, the first ivonescimab Phase 3 readout outside NSCLC.
- HARMONi-2 — now the first monotherapy head-to-head OS win over pembrolizumab itself.
The Summit-sponsored global program tells the harder half of the story. In HARMONi (global, EGFR-mutant NSCLC post-TKI), the April 2025 primary OS analysis showed a positive trend that missed significance: HR 0.79 (95% CI 0.62–1.01; p=0.057 against a required 0.0448), median OS 16.8 versus 14.0 months — while its PFS primary was a clean win at HR 0.52 (95% CI 0.41–0.66; p<0.00001). Updated analyses since: HR 0.78 (95% CI 0.62–0.98; nominal p=0.0332) at WCLC 2025, and an HR of 0.76 in both the full ITT population and the western subgroup at a June 2026 data cut-off (western median follow-up 23.2 months), shared with the FDA per the July 22, 2026 release. That BLA — ivonescimab plus chemotherapy in EGFRm NSCLC — was accepted in January 2026 with a PDUFA goal date of November 14, 2026. HARMONi-3 (global, ivonescimab plus chemotherapy versus pembrolizumab plus chemotherapy) has not read out; TD Cowen’s Tyler Van Buren wrote that HARMONi-2 “derisks” it, with results expected late this year or early next, per BioPharma Dive. HARMONi-7, the global monotherapy head-to-head in PD-L1-high first-line NSCLC that Summit says it began enrolling in 2025, is the trial the FDA will want for a monotherapy claim; BioPharma Dive reports those outcomes are expected in 2028. We have not confirmed a registry identifier for HARMONi-7 from a first-hand source, so none is linked here.
Comp context: China-originated assets keep cashing checks
The win is the data point behind a deal window we track in the daily brief. In the same 48 hours, GSK licensed Hutchmed’s KRAS-EGFR antibody for $110 million upfront (up to $1.3 billion), and Menarini took Gan & Lee’s GLP-1 to Europe in a $771 million deal; our September 4 brief counted three of the window’s four largest checks going to China-originated assets — GSK–Hutchmed, Menarini–Gan & Lee, and NeuShen’s $80 million raise. The prior day, September 1, our deals DB logged Roche paying up to $1.53 billion for Simcere’s B-cell antibody. Our deals DB holds only a handful of comparable disclosed oncology licenses from this window (2 with full upfront/total splits) — thin sample, directional only. The structural frame is the parent article’s: roughly one-third of 2025 licensing and collaboration capital went to Chinese companies, per Stifel via Ropes & Gray, and the two largest 2026 IPOs (Kailera, Braveheart) both rest on Hengrui molecules. HARMONi-2’s OS result is the strongest single piece of clinical evidence behind that flow: a China-originated molecule beating the world’s best-selling drug head-to-head on survival, twice over (PFS, then OS).
The tape: a 17% session that still leaves the stock at half its 2025 high
SMMT’s documented closes around the event, per the Yahoo Finance daily series:
| Date | Close | Move | Context |
|---|---|---|---|
| Apr 24, 2025 | $36.70 | — | Pre-interim-OS baseline |
| Apr 25, 2025 | $23.47 | −36.0% | HARMONi-2 interim OS “positive trend” only |
| May 30, 2025 | $18.22 | −30.5% | HARMONi global PFS win, OS still open |
| Sep 2, 2026 | $14.60 | — | Pre-announcement baseline |
| Sep 3, 2026 | $17.13 | +17.3% | OS significance; intraday high $17.35 |
| Sep 4, 2026 | $17.60 | +2.7% | Follow-through |
| Sep 8, 2026 | $17.64 | +0.2% | +20.8% vs Sep 2 |
Table 2: SMMT closes per Yahoo Finance. September 3 volume was 14.9 million shares, 2.7x the trailing-20-day average; the April 25, 2025 session traded 24.7 million. All moves are close-to-close.
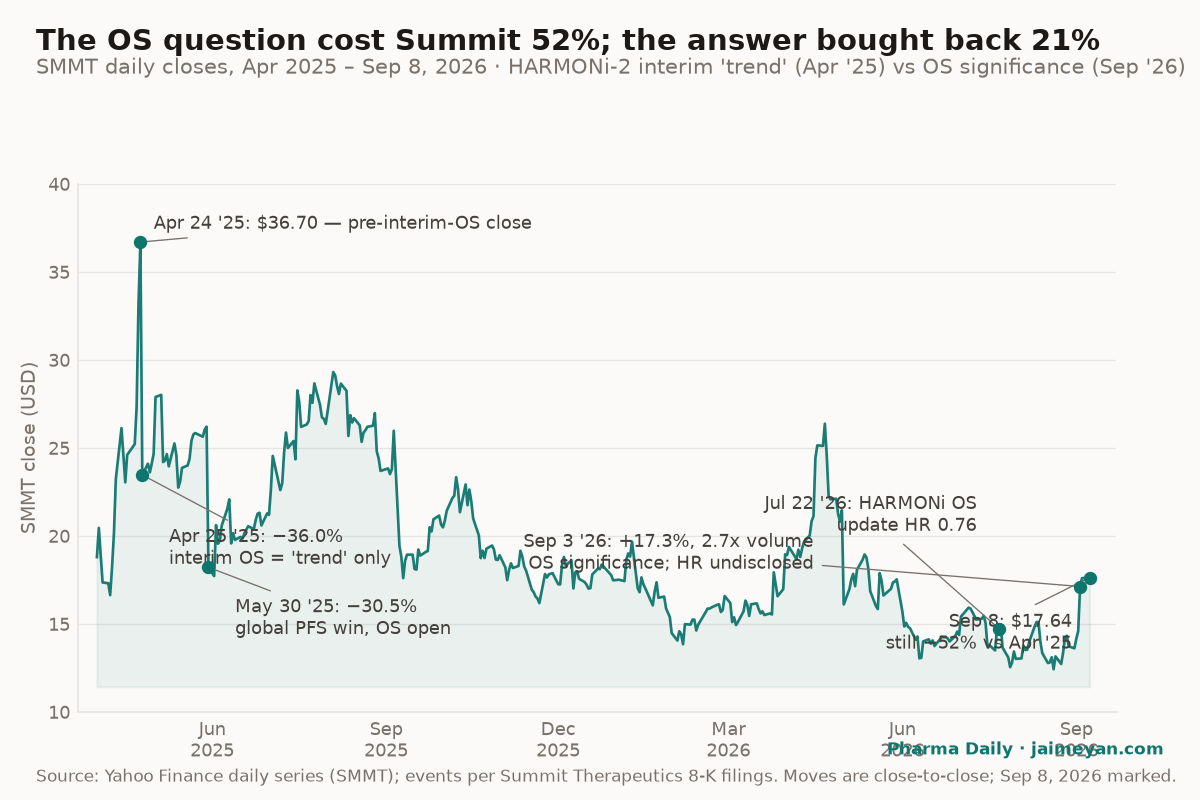
Figure 1: SMMT daily closes, April 2025 through September 8, 2026. The stock’s problem was never the PFS data — it was 17 months of OS ambiguity between the April 2025 interim trend and the September 2026 significance ruling. Even after a 20.8% run, $17.64 sits 52% below the April 24, 2025 close of $36.70.
Akeso’s Hong Kong line moved harder than the ADR once detail was digested: 9926.HK closed +3.4% on September 3, then +11.5% to HK$101.2 on September 4 on roughly double volume — a two-session gain of 15.3% — before easing to HK$96.2 on September 8. The market is pricing a WCLC reveal near the UBS estimate (HR ~0.76) and a de-risked HARMONi-3, not the China label itself: HARMONi-2 cannot anchor a US approval, as BioPharma Dive notes the FDA will require the global studies. Summit’s funding clock matters here too — cash and equivalents of $419.4 million plus $271.3 million in short-term investments at June 30, 2026 against a 10-Q statement that this is “not sufficient to fund our planned operations” for a year, meaning the PDUFA window overlaps likely financing needs.
What would change the story
- WCLC, later this month: the OS HR and CI. An HR materially worse than the ~0.76 sell-side working assumption — or a CI crossing 1 in any emphasized subgroup — takes the tape back toward the April 2025 regime.
- November 14, 2026 PDUFA: the HARMONi-based BLA decision. A CRL resets the entire Western narrative regardless of HARMONi-2’s elegance.
- HARMONi-3, late 2026 into 2027: the first global chemotherapy-combination head-to-head against pembrolizumab plus chemotherapy. TD Cowen frames HARMONi-2 as de-risking it; a miss would contradict that directly.
- Financing: any raise ahead of the PDUFA date would confirm the 10-Q’s liquidity language and reset the share count against a fixed milestone ceiling.
One Take
The HARMONi-2 OS win converts Summit’s story from “best PFS data in class, OS unresolved” to “OS resolved in China, magnitude pending” — and the 17.3% session says the market prices the significance ruling now and the HR later, which is the right order given that Akeso’s own release quantified nothing. My conviction is moderate that SMMT holds its $17–$18 range into WCLC: the position is asymmetric to the disclosed facts (a significance ruling with a PFS anchor of HR 0.51 already on file), but the stock has traded this pattern before — the April 2025 “positive trend” cost 36% in a session, and this is the same trial, same endpoint, one analysis later. What I would not underwrite is reading HARMONi-2 across to HARMONi-3 or HARMONi-7: China-only monotherapy data have limited transfer to global combination settings, and the HARMONi primary OS miss of 2025 (HR 0.79, CI 0.62–1.01) is the standing counterexample inside this same program. Falsifiers: a WCLC HR worse than 0.85, any November 14 regulatory surprise, or a financing that marks the equity down ahead of the binary.
Key takeaways
- Ivonescimab monotherapy met OS versus pembrolizumab monotherapy at a pre-specified interim of HARMONi-2 — the first double-blind Phase 3 head-to-head OS win over Keytruda — but the HR and CI are undisclosed until WCLC later this month.
- The disclosed quantitative record: PFS HR 0.51 (95% CI 0.38–0.69), median PFS 11.14 vs 5.82 months, NMPA approval April 2025; the global HARMONi OS primary missed at HR 0.79 (95% CI 0.62–1.01) before improving to 0.76 at the June 2026 cut.
- SMMT: +17.3% on September 3 on 2.7x volume, +20.8% through September 8 versus the pre-announcement close — and still 52% below its April 24, 2025 close. Akeso gained 15.3% over two Hong Kong sessions.
- The event landed in a window where three of the four largest checks went to China-originated assets — GSK–Hutchmed ($110M/$1.3B), Menarini–Gan & Lee ($771M), NeuShen ($80M) — with Roche–Simcere (up to $1.53B) logged the day before; our comp base for upfront/total splits in oncology this window is 2 deals — directional only.
- Next binaries with dates: WCLC (late September 2026), PDUFA November 14, 2026, HARMONi-3 late 2026 into 2027; Summit’s $690.7 million in cash and short-term investments is, per its own 10-Q, insufficient to fund a full year of operations.
FAQ
Did ivonescimab beat Keytruda on overall survival?
On significance, yes: the IDMC-assessed interim analysis of HARMONi-2 met its key secondary endpoint of OS for ivonescimab monotherapy versus pembrolizumab monotherapy in first-line PD-L1-positive NSCLC. The hazard ratio and confidence interval are undisclosed until the WCLC presentation later this month; UBS expects roughly a 24% reduction in the risk of death.
Does this support a US approval?
Not by itself. HARMONi-2 is a China-only trial, and the FDA will look to the global program — the HARMONi-based BLA (PDUFA November 14, 2026) and HARMONi-7 for monotherapy, with outcomes expected in 2028 per BioPharma Dive.
Why did the stock fall 36% on this same trial in April 2025?
That session’s news was an interim OS analysis requested by Chinese health authorities showing a “clinically meaningful, positive trend” — not significance. The OS question then stayed open for 17 months; the September 2, 2026 ruling is what closed it.
Sources
First-hand (filings, releases, registry):
- Summit 8-K, September 3, 2026 (HARMONi-2 OS met; HARMONi-7 noted) with press release exhibit — SEC EDGAR
- Akeso press release: ivonescimab meets OS key secondary endpoint in HARMONi-2 interim — PR Newswire, 2026-09-02
- Summit 10-Q, Q2 2026 (license terms; $419.4M cash + $271.3M short-term investments; liquidity statement; shares outstanding) — SEC EDGAR
- Summit 8-K, July 22, 2026 (HARMONi updated OS: HR 0.76 ITT and western; April 2025 primary HR 0.79, CI 0.62–1.01, p=0.057; PFS HR 0.52) — SEC EDGAR
- Summit 8-K, January 29, 2026 (BLA acceptance; PDUFA November 14, 2026) — SEC EDGAR
- Summit 8-K, May 30, 2026 (HARMONi-6 OS HR 0.66 vs tislelizumab + chemo; Lancet publication; AK112-206 mCRC data) — SEC EDGAR
- Summit 8-K, August 26, 2026 (HARMONi-GI1 significant OS in biliary tract cancer) — SEC EDGAR
- Summit 8-K, April 25, 2025 (HARMONi-2 interim OS “clinically meaningful, positive trend”) — SEC EDGAR
- Summit 8-K, September 8, 2025 (WCLC 2025 HARMONi western-patient analysis) — SEC EDGAR
- ClinicalTrials.gov: NCT05499390 (HARMONi-2, n=398 actual)
Analysis and tape context:
- Akeso, Summit cancer drug confirms lung cancer survival benefit — BioPharma Dive, 2026-09-03 (UBS ~24% risk-reduction expectation; TD Cowen de-risking read; WCLC timing; 2028 global monotherapy timeline)
- Summit, Akeso say ivonescimab clears OS bar in Phase 3 lung cancer trial — Endpoints News, 2026-09-03
- GSK to license Hutchmed’s KRAS-EGFR cancer drug for $110M upfront — Endpoints News, 2026-09-03
- Menarini signs $771M deal to take Gan & Lee GLP-1 to European market — Fierce Biotech, 2026-09-04
- Roche inks $1.53B deal for Simcere’s B-cell-targeting antibody — Fierce Biotech, 2026-09-01
- The New Biotech IPO Class: Bigger, Later-Stage, and Judged Harder — Pharma Daily (parent analysis; China-asset licensing share via Ropes & Gray/Stifel)
- Pharma Daily brief, September 4, 2026 — Pharma Daily (first coverage of the readout)
Provenance: collected 2026-09-08 via EDGAR (Summit filings and exhibits above), ClinicalTrials.gov API v2, PR Newswire, and trade press, with raw dumps under .tmp_research/summit-ivonescimab-os-2026/. Prices (SMMT and 9926.HK closes and volumes) via the Yahoo Finance daily series; percentage moves computed close-to-close; market cap of $14.1 billion uses 797,749,602 shares outstanding as of July 17, 2026 per the Q2 2026 10-Q cover. The OS hazard ratio, confidence interval, and medians for the September 2, 2026 interim are undisclosed by both companies; “undisclosed” is used rather than any estimate. The full HARMONi-2 PFS presentation date (WCLC 2024) and The Lancet publication (Xiong et al.) are per the 10-Q; no registry identifier for HARMONi-7 is confirmed from a first-hand source, so none is linked. Failed sources: Fierce Pharma’s September 3 article and the Fierce Biotech Roche–Simcere article both returned HTTP 403 at collection — the Fierce Pharma piece is excluded from Sources (no claim rests on it), and the Roche–Simcere $1.53 billion figure rests on our deals DB, which carries the original Fierce Biotech URL. Comp context on this window’s oncology licenses rests on 2 deals with full upfront/total splits in our DB — directional, not definitive. All performance figures are marked to the September 8, 2026 close and will move with the market.